Market overview and structural significance of the Recreational Space Travel Market
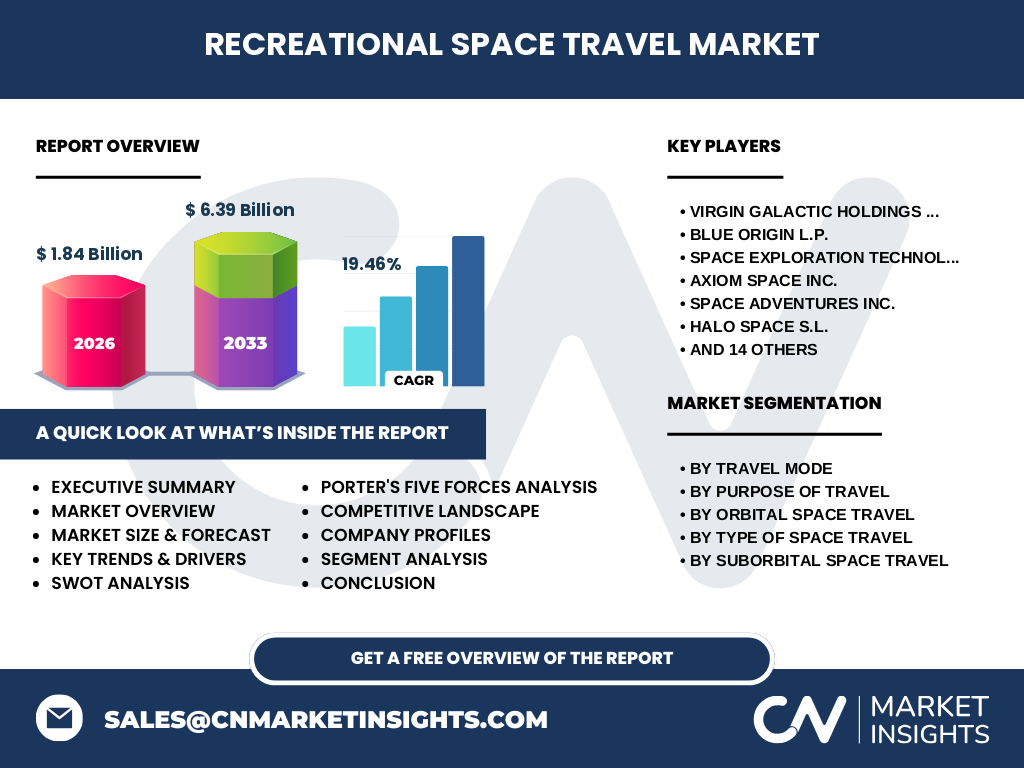
Our analysis indicates that the Recreational Space Travel Market represents a paradigm shift in aerospace, transitioning from government payloads to civilian flight. Valued at $1.84 Billion in 2026, this sector utilizes advanced carbon-composite materials and liquid-propellant engines regulated by the FAA to facilitate high-altitude passenger transit.
What are the core drivers, restraints, and challenges shaping the Recreational Space Travel Market?
The Recreational Space Travel Market industry trends highlight escalating private wealth as a primary driver, contrasted with strict environmental reviews by the Federal Aviation Administration. Logistical hurdles involve launch-site congestion and helium supply shortages, while lucrative opportunities lie in zero-gravity research tourism.
Emerging growth patterns and technological shifts in the Recreational Space Travel Market
The shift toward stratospheric ballooning championed by Space Perspective Inc. and World View Enterprises Inc. defines recent Recreational Space Travel Market analysis. These providers avoid heavy rocket g-forces, utilizing polyethylene gas balloons to offer gentle edge-of-space sightseeing.
COVID-19 impact analysis and pandemic recovery trajectory for the sector
While the pandemic delayed early flight schedules, the Recreational Space Travel Market recovered via private equity injections. Post-COVID demand surged among ultra-high-net-worth individuals, allowing pioneers like Virgin Galactic Holdings Inc. to accelerate suborbital flight test campaigns.
Competitive Benchmarking: Who dominates the Recreational Space Travel Market?
The competitive landscape features fierce rivalry between Blue Origin L.P. and Space Exploration Technologies Corp., balancing capsule reusability against rocket vertical landings. Market concentration remains high, though niche operators carve out profitable sub-segments.
Executive Summary: High-Level Findings on the Recreational Space Travel Market
Our proprietary research values the Recreational Space Travel Market market size at $1.84 Billion in 2026, projecting a robust CAGR of 19.46% through 2033. High barriers to entry protect incumbent operators holding FAA licenses.
Long-Term Market Forecast from 2027 to 2033
The data suggests the Recreational Space Travel Market will reach $6.39 Billion by 2033, driven by commercial space station habitation modules and expanding suborbital fleet capacities. This expansion relies on scaling reusable rocket infrastructure to lower per-seat costs.
Comprehensive Segmentation Analysis across Travel Modes and Objectives
Our segmentation breaks down the market into: By Travel Mode (Spacecraft, Spaceplane, Reusable Rockets, Space Capsules); By Purpose Of Travel (Leisure And Tourism, Space Adventure, Zero-Gravity Experiences); By Orbital Space Travel (Low Earth Orbit Tourism, Space Station Visits, Multi-Day Orbital Cruises); By Type Of Space Travel (Suborbital, Orbital); and By Suborbital Space Travel (Short-Duration Flights, High-Altitude Parabolic Flights, Edge-of-Space Sightseeing).
Geographic Distribution and Regional Performance Dynamics
North America dominates the Recreational Space Travel Market due to established Mojave and Cape Canaveral spaceports, alongside deep venture capital ecosystems. Meanwhile, European markets focus on stratospheric balloon concepts spearheaded by Spanish innovators like HALO Space S.L. and Zephalto SAS.
In-Depth Regional Review of North America, Europe, and Asia-Pacific
North American regulatory frameworks established by the FAA provide a clear pathway for commercial launches. In contrast, emerging Asia-Pacific markets navigate complex cross-border airspace clearances, prompting local startups like PD Aerospace Ltd. to partner with regional aerospace hubs.
Strategic Positioning of Leading Companies in the Recreational Space Travel Market
Industry leaders differentiate through varied propulsion and altitude strategies. Axiom Space Inc. targets orbital infrastructure via commercial ISS segments, whereas Space Adventures Inc. brokers bespoke orbital missions utilizing Soyuz or Crew Dragon vehicles.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of suppliers is low due to specialized aerospace manufacturing monopolies, while threat of substitutes is minimal given the unique nature of orbital flight. Rivalry among existing competitors remains intense as firms race to secure first-mover advantage in commercial passenger safety ratings.
SWOT Analysis of the Recreational Space Travel Market
Strengths include cutting-edge reusable hardware; weaknesses involve high capital expenditure requirements. Opportunities center on luxury hospitality partnerships, while threats encompass unpredictable regulatory changes by agencies like the FAA and catastrophic launch failures impacting public confidence.
Value Chain Analysis from Raw Materials to Consumer Experience
The value chain originates with titanium and carbon-fiber raw material suppliers, flowing into aerospace prime contractors, launch-provider operations, and finally concierge booking agencies such as SpaceVIP that curate ultra-exclusive itineraries for high-net-worth consumers.
High-Potential Investment Insights and Strategic Recommendations
Investors should target component manufacturers specializing in thermal protection systems and cabin life support units. Companies demonstrating rapid vehicle turnaround times will capture disproportionate market share as flight frequencies scale toward the 2033 forecast.
Conclusion and Strategic Takeaways for Industry Stakeholders
With a projected 19.46% CAGR lifting the sector to $6.39 Billion by 2033, the Recreational Space Travel Market presents massive commercial potential. Success hinges on uncompromising safety records and scalable passenger logistics.
Research Methodology and Baseline Triangulation Techniques
Our baseline estimates are triangulated by combining FAA launch license registries, primary executive interviews with operators like Orion Span Inc. and Orbital Assembly Corporation, and secondary macroeconomic indicators tracking global ultra-high-net-worth demographic expansion.
Scope of the Report, Coverage Parameters, and Analytical Limitations
This report covers global commercial civilian space travel activities through 2033, excluding uncrewed scientific payloads and government military orbital launches. Limitations include volatile testing schedules and shifting international aerospace regulatory postures.
Recent Developments, Strategic Partnerships, and Corporate Announcements
Recent industry momentum is underscored by infrastructure milestones from EOS-X Space and memorial payload expansions by Celestis Inc. Strategic alliances between tourism providers and hospitality giants continue to bridge luxury travel with orbital destination development.